What is the scope and market definition of the Military Tactical Communications Market?
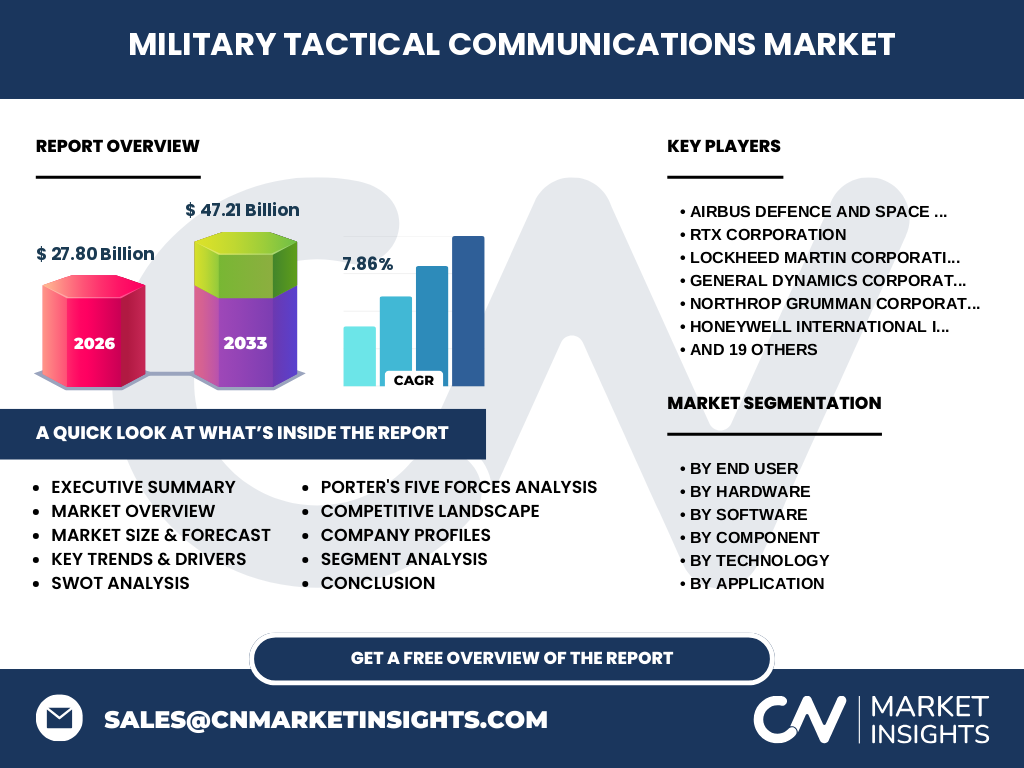
Our analysis indicates that the Military Tactical Communications Market encompasses secure voice, data, and video networking hardware, software, and services deployed by defense forces. Valued at $27.80 Billion in 2026, this sector is critical for establishing resilient battlefield connectivity across extreme environments, relying on specialized raw materials like gallium nitride for high-frequency radio components.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating geopolitical tensions demanding modernized Command and Control architectures. Based on our research, growth is restrained by stringent export controls under ITAR regulations and the high logistical cost of retrofitting legacy platforms with advanced Encryption Devices and SATCOM terminals.
Emerging Technological Shifts in the Industry
Defense organizations are rapidly transitioning toward Software-Defined Radios (SDR) and AI-driven spectrum management. Industry trends highlight a heavy reliance on specialized Signal Processing Software to counter sophisticated electronic warfare threats and frequency jamming encountered during contested multi-domain operations.
Pandemic Recovery Trajectory: COVID-19 Impact Analysis
Supply chain disruptions during the pandemic temporarily delayed component shipments for critical Power Supply Units and tactical routers. However, our analysis reveals a robust post-pandemic recovery, accelerated by government mandates to secure defense supply chains and prioritize resilient tactical communications infrastructure.
Competitive Benchmarking and Market Concentration
The landscape features high market concentration among prime contractors like RTX Corporation, Lockheed Martin Corporation, and General Dynamics Corporation. These defense giants dominate through vertically integrated portfolios spanning airborne communication systems and advanced cryptographic hardware.
Executive Summary of Key Industry Findings
The Military Tactical Communications Market is poised for significant expansion, reaching $47.21 Billion by 2033 at a CAGR of 7.86% from 2027. Situational Awareness applications and secure waveform technologies represent the primary value pools for defense investors.
Market Forecast Analysis: 2027 to 2033
Growing at a steady 7.86% CAGR, the market will expand from its 2026 baseline to hit $47.21 Billion by 2033. This trajectory reflects sustained defense budget allocations toward networked combat vehicles and digitized soldier systems.
Segmentation Analysis Across Hardware, Software, and End Users
Segmentation spans hardware (including Communication Radios and Antennas), software (featuring Mission Planning Software), and end users like the Army, Navy, and Air Force. Ground and airborne communication types account for the largest share of hardware deployments.
Geographic Distribution and Regional Performance
North America dominates the global footprint due to high defense outlays by the Department of Defense, while the Asia-Pacific region exhibits the fastest growth. Regional performance is heavily dictated by localized cross-border security disputes and ongoing military modernization initiatives.
In-Depth Regional Review of Key Markets
In Europe, procurement is galvanized by interoperability demands under NATO standards, boosting adoption of advanced Interoperability Software. Meanwhile, the Middle East market prioritizes high-bandwidth Satellite Communication (SATCOM) solutions to support vast desert operations.
Strategic Positioning of Leading Industry Participants
Key innovators such as L3Harris Technologies Inc. and Thales S.A. focus on tactical tactical networking waveforms, while companies like Elbit Systems Ltd. and Israel Aerospace Industries Ltd. specialize in electronic warfare-resilient architectures for specialized forces.
Porter's Five Forces Assessment
Supplier power remains moderate due to specialized military-grade semiconductor requirements. Conversely, buyer power is low given that sovereign defense ministries are the primary procurement agents, creating high barriers to entry backed by rigorous military qualification standards.
SWOT Analysis of the Tactical Communications Sector
Strengths include robust encryption capabilities and interoperable waveforms. Weaknesses involve complex integration hurdles. Opportunities lie in tactical 5G integration, while major threats include sophisticated cyber attacks targeting Network Management Software.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing rare-earth elements and semiconductor grade silicon, flows through Tier-1 component manufacturers producing Transceivers and Routing Equipment, and culminates with prime integrators delivering turnkey systems to the Special Forces and conventional military branches.
Strategic Investment Insights and High-Potential Areas
Investors should focus on firms developing agile, cloud-compatible Command And Control Software and quantum-resistant Data Encryption Software. These niches offer superior margins and align directly with future-proofing defense infrastructure against peer adversaries.
Conclusion and Strategic Takeaways
The Military Tactical Communications Market represents a high-barrier, high-reward sector underpinned by technological obsolescence cycles. Success requires deep integration of secure software architectures with ruggedized tactical hardware to meet evolving multi-domain operational requirements.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining defense budget registry data, primary stakeholder interviews with procurement officers, and macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing for specialized domains like Underwater Communication.
Scope of the Report and Coverage Parameters
This report covers global deployment trends across army, navy, air force, and special forces applications. Limitations exclude civil public safety radio networks unless explicitly integrated into joint military-civilian defense frameworks.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic acquisitions and cross-border partnerships aimed at enhancing tactical edge computing. Companies like Viasat Inc. and Cisco Systems Inc. have actively secured defense contracts to deploy secure tactical edge routers and resilient SATCOM payloads.